What this page covers
Ceasing South African tax residency changes your banking, your tax and how money leaves the country. The old financial emigration route no longer exists as a separate process.
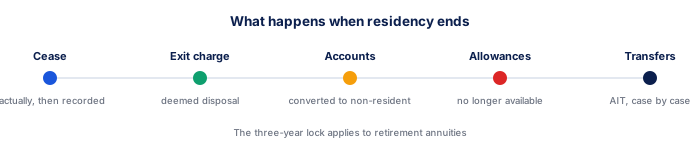
| Item | While resident | After ceasing residency |
|---|---|---|
| Tax on worldwide income | Yes | No, South African source only |
| Single discretionary allowance | R2 million a year | Not available |
| Foreign investment allowance | R10 million a year with AIT | Not available |
| Bank accounts | Resident accounts | Converted to non-resident accounts |
| Transferring funds out | Under the allowances | AIT TCS PIN, case by case |
| Exit tax | Not applicable | Deemed disposal of worldwide assets |
| Item | Rule |
|---|---|
| What triggers it | Ceasing to be a South African tax resident |
| What it taxes | A deemed disposal of worldwide assets at market value |
| What is excluded | South African immovable property, and some retirement interests |
| Rate | Capital gains tax at your applicable inclusion rate |
| When payable | In the year residency ceases |
| Asset | May still hold |
|---|---|
| South African property | Yes |
| A non-resident bank account | Yes |
| JSE shares | Yes, through a non-resident account |
| A retirement annuity | Yes, with a three-year lock before withdrawal |
| A tax-free savings account | Yes, but contributions usually stop |
How these figures work
The figures on this page come from the body that publishes them and change on a schedule rather than continuously, which is what makes them worth keeping in one place. The three-year rule on retirement annuities means someone who ceases residency cannot withdraw the full value until three years have passed since residency ended.
Ceasing tax residency is a factual question answered by the treaty tie-breaker and the physical presence test, not by filling in a form. The form records it.
★ What this means in practice
There is no longer a separate financial emigration process. What remains is a tax residency change, recorded with SARS, and the AIT route for moving funds.
✕ Common mistakes
- The three-year rule on retirement annuities means someone who ceases res. The three-year rule on retirement annuities means someone who ceases residency cannot withdraw the full value until three years have passed since residency ended.
- Ceasing tax residency is a factual question answered by the treaty tie-b. Ceasing tax residency is a factual question answered by the treaty tie-breaker and the physical presence test, not by filling in a form. The form records it.
- There is no longer a separate financial emigration process. There is no longer a separate financial emigration process. What remains is a tax residency change, recorded with SARS, and the AIT route for moving funds.
- Taking a figure without its date. A number from a reference page is only as good as when it was last checked, which is why the date sits at the top of this one.
Notes on reading these figures
- The three-year rule on retirement annuities means someone who ceases residency cannot withdraw the full value until three years have passed since residency ended.
- Ceasing tax residency is a factual question answered by the treaty tie-breaker and the physical presence test, not by filling in a form. The form records it.
- There is no longer a separate financial emigration process. What remains is a tax residency change, recorded with SARS, and the AIT route for moving funds.
To put this into practice, the Offshore Transfer Process runs the arithmetic on your own numbers; Bank Account Types covers the same ground in ordinary language; SARB FinSurv Approval goes into the detail this page only summarises; Capital Gains Tax is the related figure worth reading beside it; and Exchange Control Allowances covers what this page leaves out.
Terms used on this page
Frequently asked questions
What is the exit charge?
A deemed disposal of your worldwide assets at market value when you cease South African tax residency, taxed as a capital gain.
Do I still have allowances after ceasing residency?
No. The single discretionary and foreign investment allowances are available to residents only.
Can I keep my South African accounts?
Yes, converted to non-resident accounts, which may be transferred abroad freely.
What happens to my retirement annuity?
You keep it, but it cannot be withdrawn in full until three years have passed since residency ceased.
Is financial emigration still a process?
Not as a separate one. What remains is a tax residency change recorded with SARS, plus the AIT route for moving funds.
How is residency actually decided?
By the ordinarily resident test and the physical presence test, and by the treaty tie-breaker where two countries both claim you.
 Download this data