What this page covers
Filing season runs from July, and the deadline depends on which kind of taxpayer you are. A trader with income outside PAYE is usually a provisional taxpayer and gets the later date.
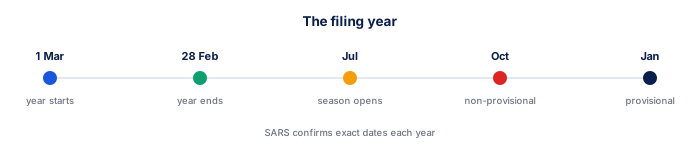
| Taxpayer | Season typically opens | Deadline |
|---|---|---|
| Auto assessed individuals | Early July | Accept or edit within the stated window |
| Individuals, not provisional | Mid July | Late October |
| Provisional taxpayers | Mid July | Late January the following year |
| Trusts | September | Late January the following year |
| Item | Date |
|---|---|
| Tax year starts | 1 March |
| Tax year ends | 28 or 29 February |
| First provisional payment | 31 August |
| Second provisional payment | Last business day of February |
| Month | What happens |
|---|---|
| March | New tax year begins |
| August | First provisional payment due |
| February | Tax year ends; second provisional payment due |
| July | Filing season opens, auto assessments issued |
| October | Deadline for non-provisional individuals |
| January | Deadline for provisional taxpayers and trusts |

Download this data
Every table on this page as a spreadsheet, with the source and the date it was checked in the header rows.
⬇ Download CSVHow these figures work
SARS builds an auto assessment from data it already holds: IRP5 certificates from employers, IT3 certificates from banks and local investment providers, and medical scheme contributions. Where that covers everything, the assessment is complete and accepting it ends the matter.
Where it does not, accepting it unchanged files an incomplete return. Nobody reports offshore broker profit to SARS on your behalf, which is precisely the situation most traders are in.
★ A worked example
A trader receives an auto assessment in early July showing a small refund, built from a salary IRP5 and a local bank IT3.
The assessment does not include R180,000 of profit from an offshore CFD account, because no certificate for it exists. Accepting it means an understated return.
The correct action is to reject the auto assessment, file a full ITR12 including the trading income, and pay the difference. Doing so voluntarily before SARS finds it avoids the understatement penalty, which runs to a percentage of the shortfall.
✕ Common mistakes
- Accepting an auto assessment with offshore income. The assessment can only include what was reported to SARS. Offshore trading profit never is.
- Assuming the provisional deadline applies to everyone. The later January deadline is for provisional taxpayers. A salaried filer has the October date and misses it easily.
- Waiting for a reminder. Filing late attracts an administrative penalty per month, whether or not tax is owed.
- Filing before the broker statements are available. An amended return is possible but attracts attention. Waiting for complete records is better than correcting later.
Notes on reading these figures
- SARS confirms the exact dates each year and they move. Treat the months above as the pattern and check the published notice before relying on a specific day.
- An auto assessment is an estimate built from third party data. It will not include trading profit from an offshore broker, because nobody reports that to SARS on your behalf. Accepting it unchanged in that situation understates your income.
- Filing late attracts an administrative penalty per month, charged whether or not tax is owed.
To put these figures to work, the Provisional Tax Deadlines runs the arithmetic on your own numbers, and Provisional Tax Calculator covers the same ground in ordinary language. Does auto assessment capture trading income? and Declaring trading income go into the detail this table only summarises.
Terms used on this page
Put this table on your own site
The table below can sit on your own page and stays current without you editing anything.
- Preview the embeddable table as it will appear on your site
To put the live table on your own page, paste this where you want it to appear. It stays current without you editing anything.
<iframe src="https://www.tradeanswers.co.za/embed/ref-sars-tax-season-dates.html" width="100%" height="620" style="border:0" title="SARS Tax Season Dates"></iframe>Free to use with attribution. The link back to this page is built into the embed.
Frequently asked questions
When does filing season open?
Usually early July for auto assessments and mid July for everyone else. SARS confirms the dates each year and they move, so check the published notice.
Am I a provisional taxpayer?
If you earn income with no PAYE deducted, above the threshold, yes. Most active traders are, which gives them the later January deadline.
What happens if I miss the deadline?
An administrative penalty per month of non-compliance, charged whether or not tax is owed, plus interest on any unpaid tax.
Can I amend a return after filing?
Yes, through a request for correction on eFiling, within the prescribed period. Doing it voluntarily is treated far better than SARS finding the omission.
Does an auto assessment include my trading profit?
Only where a South African provider issued a certificate for it. An offshore broker does not, so the assessment will be missing it.
What if I disagree with an assessment?
File a notice of objection within the period stated on the assessment, with the supporting documents. Paying under protest stops interest accruing while it is considered.