What this page covers
A trader whose income is not subject to PAYE is generally a provisional taxpayer, which means paying tax twice during the year rather than once after it. The dates below follow the tax year, 1 March to the end of February.
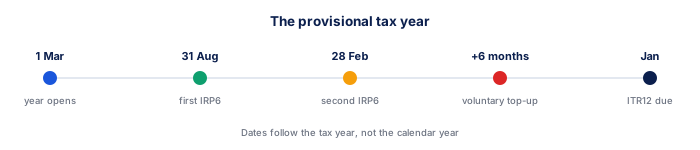
| Return | Period covered | Due |
|---|---|---|
| First IRP6 | 1 March to 31 August | 31 August |
| Second IRP6 | 1 March to 28/29 February | Last business day of February |
| Third payment, voluntary | Top-up to avoid interest | Within six months of year end for a February year end |
| ITR12 assessment | The full year | During the filing season that follows |
| Situation | Charge |
|---|---|
| Late payment | 10% of the amount not paid on time |
| Underestimation, taxable income above R1 million | 20% of the shortfall where the estimate is below 80% of the actual |
| Underestimation, taxable income R1 million or below | 20% where the estimate is below 90% of the actual and below the basic amount |
| Interest on underpayment | Charged at the prescribed rate until settled |
| Expected taxable income | Tax for the year | First IRP6, August | Second IRP6, February |
|---|---|---|---|
| R300,000 | R40,572 | R20,286 | R20,286 |
| R500,000 | R101,041 | R50,521 | R50,520 |
| R750,000 | R188,543 | R94,272 | R94,271 |
| R1,000,000 | R288,293 | R144,147 | R144,146 |

Download this data
Every table on this page as a spreadsheet, with the source and the date it was checked in the header rows.
⬇ Download CSVHow these figures work
Provisional tax is not an extra tax. It is the same income tax, paid in advance in two instalments so that SARS is not waiting a full year for tax on income that had no PAYE deducted from it.
The first payment is based on an estimate of the full year, halved. The second is the full year's estimate less what was already paid. The penalty regime is built around the second return, because by February the year is almost over and an estimate that misses badly implies the taxpayer knew better.
★ A worked example
A trader expects R520,000 of taxable income for the year.
Tax on R520,000 is R79,998 on the first R383,100 plus 31% of the R136,900 above it, which is R42,439, giving R122,437. Less the primary rebate of R17,820, the year's tax is R104,617.
The first IRP6 at the end of August is half of that, R52,309. The second, at the end of February, is the full R104,617 less the R52,309 already paid, so another R52,308, adjusted for how the year actually turned out.
✕ Common mistakes
- Estimating on the first return and never revisiting it. The second return is measured against actual income. Repeating an August estimate in February is how the underestimation penalty is triggered.
- Assuming registration is optional. SARS applies the penalties whether or not you registered. Income outside PAYE creates the obligation.
- Ignoring the basic amount. Using the last assessed figure protects against the underestimation penalty on the first return, which is why it exists.
- Leaving the second payment to the last day. It is due on the last business day of February, not the last calendar day, and a payment that clears late attracts the 10% penalty in full.
Notes on reading these figures
- The basic amount is the taxable income from the most recent assessment, increased by 8% a year where that assessment is more than eighteen months old. Using it protects against the underestimation penalty on the first return.
- The second return is the one that matters. It is measured against actual income for the full year, so an estimate made in February needs the year's trading results to be reasonably complete.
- Registering as a provisional taxpayer is not optional where the income qualifies. SARS applies the penalties whether or not you registered.
To put these figures to work, the Provisional Tax Calculator runs the arithmetic on your own numbers, and Forex Trading Tax Calculator covers the same ground in ordinary language. SARS Tax Season Dates and SARS Income Tax Tables go into the detail this table only summarises.
Terms used on this page
Put this table on your own site
The table below can sit on your own page and stays current without you editing anything.
- Preview the embeddable table as it will appear on your site
Add the code below to your own site. The table it renders is served from here, so it never goes stale.
<iframe src="https://www.tradeanswers.co.za/embed/ref-provisional-tax-deadlines.html" width="100%" height="620" style="border:0" title="Provisional Tax Deadlines"></iframe>Free to use with attribution. The link back to this page is built into the embed.
Frequently asked questions
Do I have to register as a provisional taxpayer?
If you earn income that is not subject to PAYE, and it is more than the threshold, yes. Trading profit from a broker account has no PAYE deducted, so it qualifies.
What is the basic amount?
The taxable income from your most recent assessment, increased by 8% a year if that assessment is more than eighteen months old. Estimating at least that much protects the first return.
Is there a third payment?
A voluntary top-up within six months of year end, which stops interest accruing on any shortfall. It is not a return, only a payment.
What if I make a loss?
You still file the IRP6, showing nil. Not filing attracts an administrative penalty even where no tax is due.
How is the penalty calculated?
Late payment is 10% of the unpaid amount. Underestimation is 20% of the shortfall, measured against 80% or 90% of actual depending on the income level.
Can I pay monthly instead?
SARS accepts payments against the account at any time. The two returns still have to be filed on their dates, but the money can be built up in advance.