What this page covers
A tax-free savings account removes income tax, dividends tax and capital gains tax on everything inside it. The trade-off is a hard contribution ceiling, and exceeding it is penalised at a rate that wipes out the benefit.
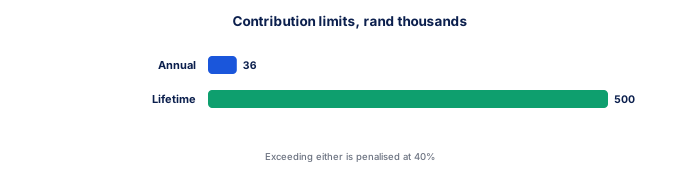
| Limit | Amount | Applies to |
|---|---|---|
| Annual contribution | R46,000 | Each tax year, 1 March to end February |
| Lifetime contribution | R500,000 | Across all accounts, for life |
| Penalty on excess | 40% | Of the amount contributed above either limit |
| Number of accounts | No limit | But the limits apply across all of them combined |
| Minimum age | None | A parent may open one for a minor, against the child's limits |
| Tax | Outside a TFSA | Inside |
|---|---|---|
| Interest | Taxed at your marginal rate above the exemption | Exempt |
| South African dividends | 20% withheld | Exempt |
| Capital gains | 40% included at your marginal rate | Exempt |
| Foreign dividends | Taxed with a partial exemption | Foreign withholding still applies |
| REIT distributions | Taxed as income | Exempt |
| Instrument | Allowed |
|---|---|
| JSE-listed ETFs | Yes, if the fund is approved for TFSA use |
| Unit trusts | Yes, most |
| Fixed deposits and bank products | Yes |
| Retail savings bonds | Yes |
| Individual JSE shares | No |
| Derivatives and CFDs | No |

Download this data
Every table on this page as a spreadsheet, with the source and the date it was checked in the header rows.
⬇ Download CSVHow these figures work
The wrapper is simple: nothing inside it is taxed, and the price of that is a ceiling on what you may put in. Both limits run at once, so a year in which you contribute R46,000 uses a year of annual room and R46,000 of the lifetime R500,000.
The penalty is what makes the limits bind. SARS raises 40% on any excess, which is more than the top marginal rate, so over-contributing is worse than not using the account at all.
★ A worked example
Someone contributes R3,833 a month, reaching R45,996 by February. In year eleven the cumulative total passes R500,000.
The amount above R500,000 is an excess contribution, so SARS raises a penalty of 40% on it, and it still counts against the lifetime limit. Stopping at R500,000 exactly, part way through year eleven, avoids the penalty entirely.
✕ Common mistakes
- Assuming a withdrawal restores room. It does not. Taking R50,000 out and replacing it costs R50,000 of the lifetime R500,000.
- Holding cash in it. The exemption is worth most on the highest-growth assets. Cash in a TFSA wastes the wrapper.
- Opening several accounts without tracking the total. The limits apply across all of them combined, and each provider only sees its own.
- Expecting foreign dividends to be exempt. Foreign withholding tax still applies. Only the South African taxes fall away.
Notes on reading these figures
- A withdrawal does not restore the contribution room it used. Taking R50,000 out and putting it back costs R50,000 of lifetime allowance, which is the single most expensive misunderstanding about these accounts.
- The 40% penalty is on the excess contribution, not on the growth. SARS raises it on assessment, and it is payable whether or not you noticed.
- Transferring between providers does not count as a contribution, provided the transfer is done directly between them rather than by withdrawing and redepositing.
To put these figures to work, the Tax-Free Savings Account Calculator runs the arithmetic on your own numbers, and Capital Gains Tax Rates and Exclusions covers the same ground in ordinary language. Can I trade in a TFSA? and Retirement Fund Contribution Limits go into the detail this table only summarises. The Which ETF should a beginner buy? covers the part this table leaves out.
Put this table on your own site
The table below can sit on your own page and stays current without you editing anything.
- Preview the embeddable table as it will appear on your site
Place this snippet on your page and the table is embedded live, rather than copied and left to age.
<iframe src="https://www.tradeanswers.co.za/embed/ref-tax-free-savings-account-limits.html" width="100%" height="620" style="border:0" title="Tax-Free Savings Account Limits"></iframe>Free to use with attribution. The link back to this page is built into the embed.
Terms used on this page
Frequently asked questions
Can I have more than one TFSA?
Yes, with different providers. The annual and lifetime limits apply to all of them added together, and no provider sees the others.
What happens if I go over the limit?
SARS raises a 40% penalty on the excess. The contribution still counts against the lifetime limit, so the room is gone as well.
Does a withdrawal free up room?
No. Contribution room is used when you contribute, and a withdrawal does not return it.
Can I hold individual shares?
No. The permitted list covers approved ETFs, unit trusts, bank products and retail savings bonds, not single shares.
Should I use a TFSA or a retirement annuity first?
They do different things. A retirement annuity gives a deduction now and locks the money; a TFSA gives no deduction but is accessible and exempt on the way out.
Is the R500,000 limit adjusted for inflation?
It has not been since the accounts were introduced, which means it falls in real terms each year.