What this page covers
Contributions to a pension fund, provident fund or retirement annuity are deductible, up to a percentage of income and a rand ceiling. Anything above the ceiling is not lost, but it is carried forward rather than deducted now.
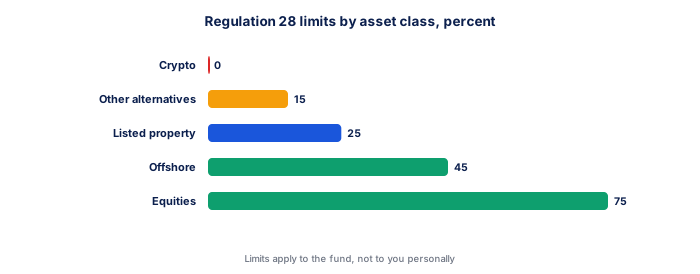
| Item | Rule |
|---|---|
| Percentage limit | 27.5% of the greater of remuneration or taxable income |
| Annual rand cap | R430,000 |
| Funds covered | Pension, provident and retirement annuity combined |
| Employer contributions | Treated as a fringe benefit, then deductible under the same limit |
| Excess above the limit | Carried forward to the next year, or set against a lump sum at retirement |
| Asset class | Maximum |
|---|---|
| Equities | 75% |
| Offshore | 45% |
| Listed property | 25% |
| Hedge funds, private equity and other | 15% combined |
| Crypto assets | 0% |
| African markets outside South Africa | 10% of the offshore allowance |
| Taxable income | 27.5% of income | Deductible this year |
|---|---|---|
| R400,000 | R110,000 | R110,000 |
| R800,000 | R220,000 | R220,000 |
| R1,200,000 | R330,000 | R330,000 |
| R1,600,000 | R440,000 | R430,000, capped |
| R2,000,000 | R550,000 | R430,000, capped |

Download this data
Every table on this page as a spreadsheet, with the source and the date it was checked in the header rows.
⬇ Download CSVHow these figures work
The deduction is the lower of two numbers: 27.5% of income and R430,000. Below roughly R1.56 million of income the percentage binds; above it the rand cap does.
Contributions above the limit are not wasted. They carry forward, and at retirement they reduce the taxable portion of the lump sum, which is why over-contributing deliberately is a recognised strategy rather than a mistake.
★ A worked example
Someone with taxable income of R900,000 contributes R300,000 to a retirement annuity.
27.5% of R900,000 is R247,500, which is below the R430,000 cap, so the deductible amount is R247,500. At a 41% marginal rate that saves R101,475 in tax.
The remaining R52,500 is carried forward to next year, or set against the lump sum at retirement. Nothing is lost, but the benefit is deferred.
✕ Common mistakes
- Assuming the cap applies at every income. It binds only above about R1.56 million. Below that the 27.5% is the effective limit.
- Forgetting employer contributions count. They are added to your income as a fringe benefit, then deducted under the same limit, so they use your room.
- Treating excess contributions as lost. They carry forward and reduce the taxable lump sum at retirement.
- Expecting Regulation 28 to apply outside the fund. It constrains the fund only. Money held personally has no such limits.
Notes on reading these figures
- The cap binds only above roughly R1.56 million of income, where 27.5% first exceeds R430,000. Below that the percentage is the effective limit.
- Trading profit that SARS treats as revenue counts toward taxable income, so it raises the amount you may contribute deductibly.
- Regulation 28 applies to the fund, not to you. Money outside a retirement fund is unconstrained, which is why offshore exposure is usually built there rather than inside the fund.
To put these figures to work, the Marginal Tax Rate Calculator runs the arithmetic on your own numbers, and Retirement annuity vs TFSA covers the same ground in ordinary language. What Regulation 28 limits and Tax-Free Savings Account Limits go into the detail this table only summarises. The SARS Income Tax Tables covers the part this table leaves out.
Put this table on your own site
The table below can sit on your own page and stays current without you editing anything.
- Preview the embeddable table as it will appear on your site
Paste the snippet below into your own page and the table appears there, updating itself as the figures change.
<iframe src="https://www.tradeanswers.co.za/embed/ref-retirement-fund-contribution-limits.html" width="100%" height="620" style="border:0" title="Retirement Fund Contribution Limits"></iframe>Free to use with attribution. The link back to this page is built into the embed.
Terms used on this page
Frequently asked questions
What is the actual limit?
27.5% of the greater of remuneration or taxable income, capped at R430,000 a year across all retirement funds combined.
Do employer contributions use my limit?
Yes. They are treated as a fringe benefit added to your income, then deducted under the same limit.
What happens to contributions above the cap?
They carry forward to later years, and at retirement they reduce the taxable portion of the lump sum.
Does trading profit raise my limit?
Where SARS treats it as revenue, yes. It increases taxable income, which raises 27.5% of that figure.
What is Regulation 28?
The limits on what a retirement fund may hold: 75% equities, 45% offshore, 25% listed property, and no crypto.
Can I contribute to more than one fund?
Yes, but the limit applies to the total across a pension fund, provident fund and retirement annuity combined.