What this page covers
South Africa has several domestic payment rails and they behave very differently. Which one a payment uses decides whether it arrives in seconds or in two days.
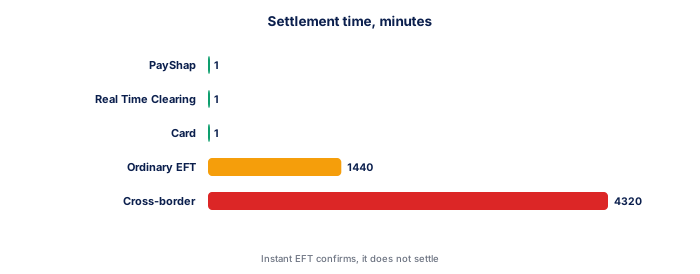
| Method | Speed | Typical cost | Limit |
|---|---|---|---|
| PayShap | Under 60 seconds | Free to about R10 | R50,000 per transaction |
| Real Time Clearing | Under 60 seconds | R40 to R60 | Bank dependent, often R250,000 |
| Ordinary EFT | 1 to 2 business days | R1 to R15 | High |
| Instant EFT, third party | Minutes, confirmation only | Merchant pays 1% to 3% | Bank dependent |
| Card | Immediate authorisation | Merchant pays 1% to 3% | Card limit |
| Debit order | On the agreed date | R2 to R15 | Mandate dependent |
| Cash deposit | Immediate | 1% to 2% of the amount | FICA reporting above R49,999.99 |
| Situation | Effect |
|---|---|
| Payment made after the daily cut-off | Processes the next business day |
| Payment made on a Friday afternoon | Often only clears on Monday or Tuesday |
| Public holiday | Not a business day for clearing |
| Payment to a different bank | Slower on ordinary EFT, same on PayShap |
| First payment to a new beneficiary | Some banks hold it for verification |
| Purpose | Best route | Why |
|---|---|---|
| Funding a local broker account | Instant EFT or RTC | Same day, verified immediately |
| Funding an offshore broker | Card or international transfer | Local rails do not cross the border |
| Small urgent transfer | PayShap | Seconds, and cheap or free |
| Regular monthly contribution | Ordinary EFT or debit order | Cheapest per transaction |
| Receiving a withdrawal | Ordinary EFT to your own account | Brokers rarely pay to a third party |
How these figures work
The figures on this page come from the body that publishes them and change on a schedule rather than continuously, which is what makes them worth keeping in one place. A broker will almost never pay a withdrawal to an account in a different name. Funding from an account that is not yours creates a problem on the way out, not on the way in.
Instant EFT services do not actually move money instantly. They confirm to the merchant that an ordinary EFT has been initiated, and the funds settle on the normal cycle.
★ What this means in practice
PayShap works by mobile number or by account number, and the proxy is what makes it quick to use rather than what makes it fast to settle.
✕ Common mistakes
- A broker will almost never pay a withdrawal to an account in a different. A broker will almost never pay a withdrawal to an account in a different name. Funding from an account that is not yours creates a problem on the way out, not on the way in.
- Instant EFT services do not actually move money instantly. Instant EFT services do not actually move money instantly. They confirm to the merchant that an ordinary EFT has been initiated, and the funds settle on the normal cycle.
- PayShap works by mobile number or by account number, and the proxy is wh. PayShap works by mobile number or by account number, and the proxy is what makes it quick to use rather than what makes it fast to settle.
- Taking a figure without its date. A number from a reference page is only as good as when it was last checked, which is why the date sits at the top of this one.
Notes on reading these figures
- A broker will almost never pay a withdrawal to an account in a different name. Funding from an account that is not yours creates a problem on the way out, not on the way in.
- Instant EFT services do not actually move money instantly. They confirm to the merchant that an ordinary EFT has been initiated, and the funds settle on the normal cycle.
- PayShap works by mobile number or by account number, and the proxy is what makes it quick to use rather than what makes it fast to settle.
To put this into practice, the Broker Deposits and Withdrawals runs the arithmetic on your own numbers; South African Bank Charges covers the same ground in ordinary language; What deposit methods work in SA goes into the detail this page only summarises; FICA Requirements is the related figure worth reading beside it; and Card and Cross-Border Fees covers what this page leaves out.
Terms used on this page
Frequently asked questions
How fast is PayShap?
Under a minute, with a limit of R50,000 per transaction at most banks.
Is instant EFT actually instant?
No. It confirms to the merchant that an EFT has been initiated. The funds settle on the normal cycle.
Why did my Friday payment only arrive Tuesday?
Ordinary EFT clears on business days. A payment after the Friday cut-off processes on Monday and may credit on Tuesday.
Can I fund a broker from someone else's account?
You can, but the withdrawal will be a problem. A broker pays out only to an account in the client's own name.
What is DebiCheck?
An authenticated debit order mandate. You approve it at setup, which makes it harder to abuse and harder to dispute afterwards.
What does a cash deposit cost?
Typically 1% to 2% of the amount, which on regular use exceeds the whole monthly account fee.
 Download this data